It is February. Your accountant is calling. Your HR is sending reminder emails. And you are staring at the same question you face every March:
“Where do I put this ₹1.5 lakh before the financial year ends?”
Most people answer this question in a hurry — they call their insurance agent who recommends a ULIP, or they quickly open a tax-saving FD, or they dump everything into their parents’ suggested LIC policy.
Years later, they realise they paid enormous charges, earned poor returns, and missed the investments that would have built real wealth alongside saving tax.
This guide ends that cycle.
Here is the definitive, data-driven comparison of every major Section 80C tax-saving investment available in 2025 — so you make this decision once, correctly, and in April rather than March.
👉 Compare all tax-saving options for your income with our free Tax Saving Investment Calculator →
The Foundation: What is Section 80C?
Section 80C of the Income Tax Act allows you to reduce your taxable income by up to ₹1,50,000 per financial year by investing in approved instruments.
At the 30% tax bracket — this saves ₹46,800 per year (₹45,000 tax + ₹1,800 cess). At the 20% tax bracket — this saves ₹31,200 per year. At the 10% tax bracket — this saves ₹15,600 per year.
Critical note: Section 80C deductions are available only under the old tax regime. If you have opted for the new tax regime — Section 80C does not apply. For most home loan borrowers and investors, the old regime still saves more tax overall.
What already counts toward your ₹1.5 lakh 80C limit without any extra action:
- Employee EPF contribution (12% of basic salary)
- Home loan principal repayment
- Children’s tuition fees (up to 2 children)
- Life insurance premium (if already paying)
Always calculate how much of the ₹1.5 lakh is already being used by these automatic contributions before deciding how much additional 80C investment is needed.
👉 Related Reading: Income Tax Calculator 2025 — Save Maximum Tax Legally → — the complete guide to all available tax deductions beyond just Section 80C.
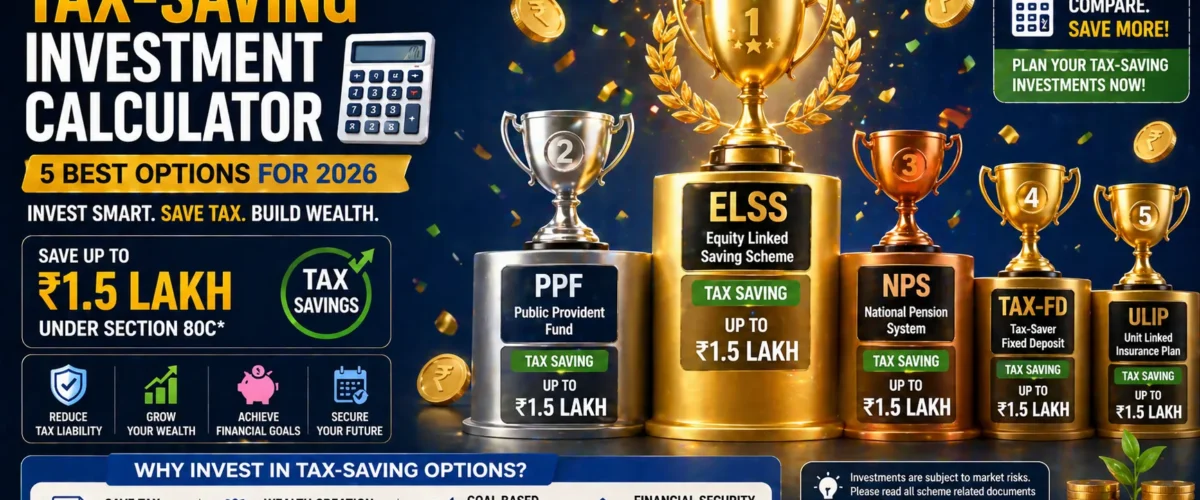
The 5 Best Tax-Saving Investments 2025: Complete Comparison
| Investment | Returns | Risk | Lock-in | Tax on Returns | Best For |
|---|---|---|---|---|---|
| ELSS Mutual Funds | 12–15% (market-linked) | Medium-High | 3 years (shortest) | LTCG 12.5% above ₹1.25L | Long-term wealth building with tax saving |
| PPF | 7.1% (guaranteed) | Zero | 15 years | Completely tax-free | Risk-averse, long-term corpus building |
| NPS Tier 1 | 8–12% (market-linked) | Low-Medium | Until retirement (age 60) | 60% tax-free; 40% annuity (taxable) | Retirement-focused with extra ₹50K deduction |
| Tax-Saving FD | 6.5–7.5% | Zero | 5 years (minimum) | Taxable at slab rate | Conservative investors needing guaranteed returns |
| ULIP | 6–10% (variable) | Medium | 5 years | Tax-free if conditions met | Those needing combined insurance + investment |
Option 1: ELSS Mutual Funds — The Wealth Builder’s Choice
ELSS (Equity Linked Saving Scheme) is the only pure equity investment qualifying for Section 80C deduction — and it consistently delivers the highest long-term returns of any 80C option.
Why ELSS Wins for Most Investors
Shortest lock-in of any 80C instrument: Just 3 years — compared to 5 years for Tax-FD, 15 years for PPF, and until retirement for NPS. Each SIP instalment has its own 3-year lock-in from the date of investment.
Highest return potential: Historically 12–15% CAGR over 7+ year periods — significantly above the 7.1% PPF rate.
Tax-efficient returns: LTCG above ₹1.25 lakhs taxed at 12.5% — far better than FD interest taxed at your slab rate (up to 30%).
Dual benefit: Every rupee invested saves tax today AND builds wealth for the future. No other 80C option delivers this combination as effectively.
ELSS: 10-Year and 20-Year Return Comparison
| Investment Period | ₹12,500/month ELSS SIP | ₹1,50,000 Annual Lumpsum ELSS | Total Invested |
|---|---|---|---|
| 10 years | ₹28,90,530 | ₹27,26,340 | ₹18,00,000 |
| 15 years | ₹63,07,200 | ₹59,54,660 | ₹27,00,000 |
| 20 years | ₹1,24,94,350 | ₹1,17,89,000 | ₹36,00,000 |
(Assumed: 13% annual return — conservative ELSS long-term average)
ELSS vs Other 80C Options: The Wealth Gap
| Strategy | Monthly Investment | Period | Total Invested | Final Corpus | Difference |
|---|---|---|---|---|---|
| ELSS (13%) | ₹12,500 | 20 years | ₹36,00,000 | ₹1,24,94,350 | Baseline |
| PPF (7.1%) | ₹12,500 | 20 years | ₹36,00,000 | ₹65,12,000 | −₹59,82,350 |
| Tax-Saving FD (7%) | ₹12,500 | 20 years | ₹36,00,000 | ₹63,94,000 | −₹61,00,350 |
After 20 years of consistent 80C investing — ELSS generates ₹60 lakhs MORE than PPF and FD on the same ₹12,500/month investment. This is the compounding advantage of higher equity returns over two decades.
How to Invest in ELSS: Step-by-Step
- Choose between SIP and lumpsum: SIP (₹500–₹12,500/month) spreads risk and builds discipline. Lumpsum works for large one-time investments.
- Select a fund: Consider funds with 5–10 year track record, consistent performance across market cycles, and AUM above ₹2,000 crore. Top-rated ELSS funds by research houses are a good starting point.
- Start early in the financial year: April SIP over 12 months is far better than a March lumpsum. Market timing risk is eliminated and cost averaging improves returns.
- Do not redeem immediately at 3 years: The 3-year lock-in is the minimum. ELSS generates its best returns when held 7–10 years. Redeem only for specific goals.
- Use the annual ₹1.25 lakh LTCG exemption: After the 3-year lock-in, use our Capital Gains Tax Calculator to harvest up to ₹1.25 lakhs of LTCG annually — completely tax-free.
👉 Related Reading: Capital Gains Tax Calculator — Stocks, Property & Crypto → — understanding ELSS LTCG tax and the annual exemption strategy. 👉 Related Reading: How to Become a Millionaire with SIP Calculator → — ELSS SIP as the foundation of long-term wealth building.
Option 2: PPF (Public Provident Fund) — The Guaranteed Wealth Builder
PPF is the gold standard of risk-free long-term saving in India — a government-backed instrument with guaranteed returns, complete capital safety, and entirely tax-free maturity proceeds.
PPF: Key Features 2025
| Feature | Details |
|---|---|
| Current Interest Rate | 7.1% per annum (compounded annually) |
| Government Backing | Full sovereign guarantee — zero credit risk |
| Annual Investment | Minimum ₹500, Maximum ₹1,50,000 |
| Tenure | 15 years (extendable in 5-year blocks) |
| Tax on Returns | EEE — Exempt at investment, exempt during growth, exempt at maturity |
| Premature Withdrawal | Partial withdrawal from Year 7; full closure after 15 years |
| Loan Against PPF | Available from Year 3 to Year 6 |
| Available At | Post offices, nationalised banks, authorised private banks |
PPF Triple Tax Exemption (EEE): Why It Is Unique
PPF enjoys the rare EEE (Exempt-Exempt-Exempt) status:
- Exempt at investment: ₹1.5 lakh deductible under 80C
- Exempt during growth: Annual interest earned is not taxable
- Exempt at maturity: Entire maturity amount — principal + all interest — is completely tax-free
This triple exemption means a 30% bracket taxpayer investing ₹1.5 lakhs in PPF effectively earns:
- Tax saving today: ₹46,800 (30% of ₹1.5L)
- Zero tax on 7.1% interest annually
- Zero tax on maturity
The effective post-tax return on PPF for a 30% bracket investor is approximately 10.1% equivalent (since you would need to earn 10.1% in a taxable instrument to net the same 7.1% after paying 30% tax).
PPF: 15-Year Growth Table
| Year | Annual Investment | Cumulative Investment | Interest Earned That Year | Closing Balance |
|---|---|---|---|---|
| Year 1 | ₹1,50,000 | ₹1,50,000 | ₹10,650 | ₹1,60,650 |
| Year 3 | ₹1,50,000 | ₹4,50,000 | ₹33,938 | ₹5,13,318 |
| Year 5 | ₹1,50,000 | ₹7,50,000 | ₹61,268 | ₹9,23,614 |
| Year 7 | ₹1,50,000 | ₹10,50,000 | ₹93,461 | ₹14,07,534 |
| Year 10 | ₹1,50,000 | ₹15,00,000 | ₹1,49,572 | ₹22,56,567 |
| Year 13 | ₹1,50,000 | ₹19,50,000 | ₹2,22,437 | ₹33,53,820 |
| Year 15 | ₹1,50,000 | ₹22,50,000 | ₹2,79,000 | ₹40,68,209 |
₹22.5 lakhs invested over 15 years grows to ₹40.68 lakhs — completely tax-free. The government effectively contributes ₹18.18 lakhs in interest on your savings.
ELSS vs PPF: The Most Important Comparison
| Feature | ELSS | PPF | Winner |
|---|---|---|---|
| Expected Returns (15 yr) | ~13% CAGR | 7.1% guaranteed | ELSS |
| Risk | Market risk | Zero | PPF |
| Lock-in | 3 years | 15 years | ELSS |
| Tax on Returns | LTCG 12.5% (above ₹1.25L) | Completely tax-free | PPF |
| Corpus (₹12,500/month, 15 yr) | ₹63,07,200 | ₹40,68,209 | ELSS (+₹22.4L) |
| Liquidity | High (post lock-in) | Low (15yr commitment) | ELSS |
| Psychological Safety | Low (market fluctuations) | High (guaranteed) | PPF |
Verdict: ELSS wins on returns and flexibility. PPF wins on safety, guaranteed returns, and complete tax-free status. The optimal strategy for most investors: 60–70% ELSS + 30–40% PPF — balancing wealth maximisation with a guaranteed, tax-free base.
Option 3: NPS (National Pension System) — The Retirement Supercharger
NPS is the most underutilised tax-saving instrument in India — primarily because most investors do not understand its unique extra deduction and the genuine wealth it can build for retirement.
The NPS Extra Deduction Advantage
NPS Tier 1 provides two separate tax benefits:
Benefit 1 — Section 80CCD(1): NPS contribution up to 10% of salary qualifies under Section 80C — within the overall ₹1.5 lakh limit.
Benefit 2 — Section 80CCD(1B): An additional ₹50,000 deduction over and above the ₹1.5 lakh 80C limit — exclusively for NPS.
Combined: Section 80C (all instruments): ₹1,50,000 Section 80CCD(1B) (NPS extra): ₹50,000 Total maximum deduction: ₹2,00,000
At 30% bracket + cess, the extra ₹50,000 NPS deduction saves ₹15,600 per year — on top of the ₹46,800 from 80C. Total annual saving: ₹62,400.
NPS Returns: Performance Analysis
| NPS Fund Type | 10-Year Return (Approximate) | Risk Level | Investment Profile |
|---|---|---|---|
| Equity (E) — Max 75% allocation | 12–14% | High | Pure equity, market-linked |
| Corporate Bonds (C) — Max 100% | 8–10% | Medium | Debt — corporate bonds |
| Government Securities (G) — Max 100% | 7–9% | Low | Sovereign bonds |
| Alternative Assets (A) — Max 5% | 8–12% | Medium-High | REITs, InvITs, AIFs |
Auto Choice (Lifecycle Fund): Automatically adjusts allocation based on age — high equity (75%) in youth, gradually shifting to debt as retirement approaches. Ideal for those who do not want to manage allocation.
Active Choice: You control the allocation between E, C, G, and A funds. Best for investors who want maximum equity exposure (75% cap) for higher returns.
NPS Tax Treatment at Maturity: What You Must Know
NPS tax treatment at retirement (age 60) is more complex than PPF:
| NPS Maturity Component | Tax Treatment |
|---|---|
| 60% of corpus (lump sum withdrawal) | Completely tax-free |
| 40% of corpus (mandatory annuity) | Annuity purchase is tax-free; annuity income is taxable at slab rate |
Example: NPS corpus at 60: ₹1,00,00,000 (₹1 crore) 60% lump sum: ₹60,00,000 — Tax-free ✅ 40% annuity: ₹40,00,000 invested in annuity — Monthly income ~₹25,000/month Tax on ₹25,000/month annuity income: At retirement slab rate (probably 0–5% if no other income)
The 40% annuity requirement is NPS’s main limitation compared to PPF — you cannot access the full corpus as a lump sum. However, the 60% tax-free lump sum is still a substantial amount, and the annuity provides guaranteed lifetime income.
Who Should Choose NPS?
- Salaried professionals in 30% bracket who want the extra ₹50,000 deduction (saves ₹15,600 extra per year)
- Government employees for whom NPS is the mandatory pension system
- Those who need disciplined retirement saving — the lock-until-60 structure prevents premature withdrawal
- Investors willing to accept 40% annuitisation in exchange for tax-deferred compounding over decades
Option 4: Tax-Saving Fixed Deposit — The Conservative Choice
Tax-Saving FD is the simplest 80C option — a regular fixed deposit with a 5-year lock-in that qualifies for Section 80C deduction. Zero complexity, guaranteed returns, capital safety.
Tax-Saving FD: Key Features 2025
| Feature | Details |
|---|---|
| Current Rates | 6.5–7.5% per annum (varies by bank) |
| Risk | Zero — DICGC insured up to ₹5 lakhs |
| Lock-in | 5 years (mandatory, no premature withdrawal) |
| Tax on Returns | Fully taxable at income slab rate |
| TDS on Interest | 10% TDS if interest exceeds ₹40,000/year (₹50,000 for seniors) |
| Available At | All scheduled commercial banks; post office (NSC is equivalent) |
| Nomination | Available |
| Loan Against FD | Not available during lock-in period |
The Hidden Tax Cost of Tax-Saving FD
While called a “tax-saving” instrument — the interest on a Tax-Saving FD is fully taxable at your income slab rate. For a 30% bracket investor:
Tax-Saving FD: 7.0% nominal return
Tax at 30% on interest: −2.1%
Post-tax return: 4.9%
Inflation (6%): −6%
Real post-tax return: −1.1% (NEGATIVE real return)
A 30% bracket taxpayer in a Tax-Saving FD is actually losing real purchasing power after tax and inflation. This is the fundamental problem with Tax-Saving FD for high-income investors.
However, for investors in the 0–5% tax bracket (income below ₹5 lakhs after deductions) — Tax-Saving FD’s post-tax return is close to the nominal 7% — making it genuinely competitive with PPF.
When Tax-Saving FD Makes Sense
| Investor Profile | Suitable for Tax-Saving FD? | Better Alternative |
|---|---|---|
| 0% tax bracket | Yes — post-tax return near 7% | PPF slightly better (EEE) |
| 5% tax bracket | Yes — post-tax ~6.65% | PPF/NSC comparable |
| 20% tax bracket | Marginal | PPF much better (EEE) |
| 30% tax bracket | No — post-tax 4.9%, negative real return | ELSS or PPF |
| Needs guaranteed returns | Yes — zero risk | Compare with NSC/PPF |
| Has existing 80C gap in March | Yes — quick, no market timing needed | Plan earlier for better options |
Option 5: ULIP (Unit Linked Insurance Plan) — When It Makes Sense
ULIP combines life insurance with investment — a portion of your premium goes toward insurance coverage, the rest is invested in funds of your choice. Returns are market-linked but with high first-year charges.
ULIP Pros and Cons
| ULIP Pros | ULIP Cons |
|---|---|
| Insurance + investment in one product | Very high charges in years 1–3 (15–25% of premium) |
| Tax-free maturity if sum assured ≥ 10x premium | Post-Budget 2021: maturity taxable if annual premium > ₹2.5 lakhs |
| Lock-in of only 5 years | Returns significantly drag vs standalone ELSS due to charges |
| Some flexibility to switch between fund options | Complex to understand — most buyers do not know total charges |
| Premium qualifies for 80C | Mixing insurance and investment rarely optimal |
ULIP vs ELSS + Term Plan: The Math
Most financial advisors recommend a “buy term, invest the rest” strategy over ULIP:
| Strategy | Annual Investment | After 20 Years | Tax Benefit |
|---|---|---|---|
| ULIP (₹1,50,000 premium) | ₹1,50,000 | ₹2,10,00,000 approx (6% returns after charges) | 80C + tax-free maturity |
| ELSS SIP (₹1,30,000) + Term Insurance (₹20,000 for ₹1Cr cover) | ₹1,50,000 | ₹4,13,00,000 approx (ELSS 13% returns) | 80C on ELSS + 80C on term premium |
Same ₹1.5 lakh annual investment — ELSS + Term Plan generates ₹2 crore MORE over 20 years than ULIP, while providing equal or better insurance cover.
When ULIP Is Acceptable
- When you genuinely need the forced discipline of a premium structure that combines insurance
- When your annual premium is below ₹2.5 lakhs (tax-free maturity applies)
- For NRI investors who have limitations on certain mutual fund investments
- When a very long-term (20+ year) horizon reduces the charge impact significantly
The Optimal 80C Strategy for Every Income Level
Rather than choosing just one instrument — the most effective 80C strategy combines multiple options based on your income, risk tolerance, and goals:
Strategy 1: Young Professional (Age 22–32, Income ₹6–₹12L)
Goal: Maximum wealth building while saving tax
| Instrument | Monthly | Annual | % of 80C |
|---|---|---|---|
| ELSS SIP | ₹8,000 | ₹96,000 | 64% |
| PPF | ₹4,500 | ₹54,000 | 36% |
| Total 80C | ₹12,500 | ₹1,50,000 | 100% |
Plus: ₹4,167/month NPS for extra ₹50,000 Section 80CCD(1B) deduction.
Rationale: Heavy ELSS allocation maximises long-term wealth building. PPF provides guaranteed base and liquidity backstop. NPS captures extra tax benefit.
Strategy 2: Mid-Career Professional (Age 32–45, Income ₹15–₹25L)
Goal: Balance wealth building with retirement and income protection
| Instrument | Monthly | Annual | % of 80C |
|---|---|---|---|
| ELSS SIP | ₹6,250 | ₹75,000 | 50% |
| PPF | ₹4,167 | ₹50,000 | 33% |
| NPS Tier 1 | ₹2,083 | ₹25,000 | 17% |
| Total 80C | ₹12,500 | ₹1,50,000 | 100% |
Plus: Additional ₹25,000 in NPS (beyond 80C allocation) for extra 80CCD(1B) deduction. Note: EPF already contributing ₹57,600 annually — so actual additional investment may only be ₹92,400 to fill the 80C gap.
Strategy 3: Senior Professional (Age 45–58, Income ₹25L+)
Goal: Capital preservation + retirement focus + tax saving
| Instrument | Monthly | Annual | % of 80C |
|---|---|---|---|
| PPF | ₹6,250 | ₹75,000 | 50% |
| NPS Tier 1 | ₹4,167 | ₹50,000 | 33% |
| ELSS SIP | ₹2,083 | ₹25,000 | 17% |
| Total 80C | ₹12,500 | ₹1,50,000 | 100% |
Rationale: Shift toward capital preservation as retirement approaches. PPF provides guaranteed tax-free returns. NPS builds retirement corpus. Smaller ELSS allocation maintains some equity exposure.
Strategy 4: Conservative Investor (Any Age, Risk-Averse)
Goal: Guaranteed returns + tax saving + simplicity
| Instrument | Monthly | Annual | % of 80C |
|---|---|---|---|
| PPF | ₹8,333 | ₹1,00,000 | 67% |
| Tax-Saving FD | ₹4,167 | ₹50,000 | 33% |
| Total 80C | ₹12,500 | ₹1,50,000 | 100% |
Note: This strategy sacrifices significant long-term returns for complete safety. Only appropriate for genuinely risk-averse investors who would otherwise park money in a savings account.
Beyond 80C: The Complete Tax-Saving Investment Ecosystem
Section 80C is just the beginning. Smart tax planning uses multiple deduction sections simultaneously:
| Section | Instrument | Extra Deduction | Annual Tax Saving (30%) |
|---|---|---|---|
| 80C | ELSS + PPF + EPF + others | ₹1,50,000 | ₹46,800 |
| 80CCD(1B) | NPS Tier 1 (extra) | ₹50,000 | ₹15,600 |
| 80D | Health Insurance | ₹25,000–₹1,00,000 | ₹7,800–₹31,200 |
| 24(b) | Home Loan Interest | ₹2,00,000 | ₹62,400 |
| 80E | Education Loan Interest | No limit | Full interest saving |
| 80G | Charitable Donations | 50–100% of donation | Varies |
| TOTAL MAXIMUM | ₹5,25,000+ | ₹1,63,800+ |
A ₹25 lakh income professional claiming all available deductions can reduce their effective tax rate from 25% to under 10% — legally and correctly.
👉 Related Reading: Income Tax Calculator 2025 — Save Maximum Tax Legally → — maximising every deduction beyond just Section 80C. 👉 Related Reading: How to Save Tax Using Home Loan — Complete Guide → — the home loan tax benefits that combine with 80C.
The March Rush Trap: Why April Planning Saves More
The single most expensive tax planning mistake: waiting until March to decide on 80C investments.
The March Rush Problem:
- Markets may be at year-high — ELSS lumpsum in March risks a poor entry point
- Emotional panic buying — poorly chosen products, wrong insurance policies
- All investment in one month — no SIP averaging benefit
- Tax benefit identical to April investment — but 11 months of returns lost
The April Advantage:
| Investor | When Invested | Monthly SIP | Total Invested | 20-Year Corpus | Advantage |
|---|---|---|---|---|---|
| Shreya (April SIP) | April — 12 equal monthly SIPs | ₹12,500/month | ₹36,00,000 | ₹1,24,94,350 | Baseline |
| Rahul (March lumpsum) | March — one lumpsum | ₹1,50,000/year | ₹36,00,000 | ₹1,17,89,000 | −₹7,05,350 |
By investing monthly from April instead of a lumpsum in March — Shreya’s 20-year corpus is ₹7 lakhs larger on the same total investment. The early start and SIP averaging compound significantly over 20 years.
Tax-Saving Investments for NRIs: Special Considerations
Non-Resident Indians face different rules for 80C investments:
| Instrument | NRI Eligible? | Special Conditions |
|---|---|---|
| ELSS | ✅ Yes | Repatriation restrictions may apply; KYC with NRI status |
| PPF | ❌ No | NRIs cannot open new PPF accounts; existing ones continue until maturity |
| NPS | ✅ Yes | NRI can contribute to NPS Tier 1; repatriation allowed on maturity |
| Tax-Saving FD | ✅ Yes | NRE FDs are tax-free in India; FCNR deposits also available |
| NSC | ❌ No | National Savings Certificates not available to NRIs |
| ULIP | ✅ Yes | With insurance regulatory compliance |
NRI’s best 80C option: ELSS SIP (if staying linked to India for 80C benefit) or Tax-Saving FD (simple, certain, NRI-compliant). NRIs must also ensure they have Indian income against which to claim the 80C deduction — the deduction is only valuable if you are filing Indian income tax returns.
Frequently Asked Questions
Q: Is ELSS really better than PPF for tax saving? A: For wealth building — yes, significantly. ELSS’s 13% historical return vs PPF’s 7.1% generates ₹60 lakhs more over 20 years on the same monthly investment. However, ELSS carries market risk (portfolio can fall 30–40% in bad years) while PPF is guaranteed. The ideal solution for most investors is a combination — majority ELSS for growth, minority PPF for guaranteed base.
Q: Can I invest in multiple 80C instruments simultaneously? A: Yes — and you should. Split your ₹1.5 lakh across ELSS, PPF, and NPS to balance growth, safety, and retirement saving. The total across all instruments must not exceed ₹1.5 lakh for the Section 80C deduction (with the separate ₹50,000 for NPS 80CCD(1B)).
Q: Should I invest in ELSS as SIP or lumpsum? A: SIP is almost always better — it provides rupee cost averaging, removes market timing stress, and forces consistent discipline. A monthly ELSS SIP of ₹12,500 started in April is dramatically better than a ₹1.5 lakh lumpsum panic-invested in March. The only exception: if markets have fallen 20%+ and you have a lumpsum available — a tactical lumpsum at depressed prices can be beneficial.
Q: Is ULIP good for tax saving? A: For most investors — no. ULIP’s high first-year charges (15–25% of premium) drag returns significantly below standalone ELSS. The “buy term, invest the rest in ELSS” strategy generates approximately ₹2 crore more over 20 years on the same annual investment. ULIP only makes sense for investors who need the combined insurance-investment discipline or have specific NRI or repatriation requirements.
Q: What is the NPS lock-in and is it too long? A: NPS locks your investment until age 60 — which is genuinely long. However, this is the point: NPS is specifically designed as a retirement instrument. For the 80CCD(1B) extra ₹50,000 deduction — treat NPS contributions as retirement money that you mentally write off until 60. The extra ₹15,600 annual tax saving on ₹50,000 NPS investment effectively reduces your net NPS contribution to ₹34,400 — a reasonable price for guaranteed retirement savings.
Q: Can I claim 80C even if I choose the new tax regime? A: No — Section 80C, 80CCD(1B), 80D, and most other deductions are exclusively available under the old tax regime. If you opt for the new tax regime (which is the default), you lose all these deductions. The new regime only provides the standard deduction (₹75,000 for salaried) and Section 80CCD(2) (employer NPS contribution). For most investors with significant 80C investments, the old regime saves more tax.
Conclusion
The best tax-saving investment is not the one your insurance agent recommends in February. It is the one you choose in April — after understanding your actual financial goals, risk tolerance, and income profile.
Here is the decision in its simplest form:
For most working professionals under 45: ELSS (60–70%) + PPF (20–30%) + NPS for the extra ₹50,000 deduction. This combination maximises both current tax saving and long-term wealth creation.
For risk-averse investors or those near retirement: PPF (50–60%) + NPS (30%) + Tax-FD (10–20%). This prioritises safety and guaranteed returns over maximum corpus.
For everyone: Start in April, not March. Invest monthly through SIP, not as a year-end lumpsum. Compare old vs new regime annually. Never let the March deadline force you into a product you do not understand.
The ₹1.5 lakh Section 80C limit, combined with the extra ₹50,000 NPS deduction, gives every salaried Indian a powerful government-provided incentive to invest ₹2 lakhs annually toward their financial goals. The only question is whether you deploy it intelligently — or waste it on products that serve the seller more than the buyer.
Use our Tax Saving Investment Calculator to find the optimal 80C split for your exact income, tax bracket, and financial goals.
👉 Compare all tax-saving investments for your income with our free Tax Saving Investment Calculator → 👉 Related Reading: Income Tax Calculator 2025 — Save Maximum Tax Legally → 👉 Related Reading: How to Become a Millionaire with SIP Calculator → 👉 Related Reading: SIP vs FD vs RD — Which Gives More Returns in 2025? → 👉 Related Reading: Capital Gains Tax Calculator — Stocks, Property & Crypto → 👉 Related Reading: How to Save Tax Using Home Loan — Complete Guide → 👉 Related Reading: Salary After Tax Calculator — What’s Your Real Take-Home? → 👉 Related Reading: How Much SIP Per Month to Retire at 45? →